
What Richmond-area builders were offering as of November 8, plus the deadlines and fine print to check before you sign.
Published November 8, 2026. Updated November 9, 2026. Offer details reflect research on November 8, 2026, with Eastwood’s offers rechecked on November 9.
Black Friday falls on Friday, November 27, 2026, but some Richmond-area builders aren’t waiting. Of the offers I reviewed, only Lennar used the Black Friday name, and its published contract windows have now closed. The others were November or holiday offers, and none of their posted deadlines had passed as of my research. Below is what each builder’s own page or flyer said as of Sunday, November 8, 2026, and the restrictions that matter.
Terms change fast. Before you sign, get the current offer, the eligible home, the required lender, and the deadline in writing.
Lennar’s Black Friday Sales Event: expired under its published dates
Lennar’s Black Friday Sales Event page lives in its VA/DC Metro section, and the legal copy covers “select new homes in Virginia.” It’s not a Richmond-wide sale. On November 8 the page listed homes in a handful of Greater Richmond communities, including Harpers Mill in Chesterfield, Creekside Run and Everstone in Richmond, and Watermark in North Chesterfield. It also listed homes in Northern Virginia, Williamsburg, Charlottesville, and other markets. Only a listed, qualifying homesite counts.
Lennar headlines 3 offers: reduced pricing on select homes (no dollar amount stated), an included washer and dryer on select homes (approximate retail value up to $2,900), and “up to $50,000 in Flex Credit.” According to the footnote, the Flex Credit:
- Won’t exceed $50,000, “as determined on your Loan Estimate,” so treat $50,000 as a cap, not a typical amount
- Can go toward discount points to buy down your rate or toward closing costs, but not both, and can’t be split
- Requires financing through Lennar Mortgage, LLC (you can still buy with another lender, but you won’t get this credit)
- Is limited to 1 per household and can’t be combined with other existing promotions
Lennar doesn’t publish a rate, APR, credit-score minimum, or down-payment minimum for the buydown option.
The dates were the catch, because the page gave 2 versions. The summary said to sign between November 6 and November 7, 2026, and close by November 20. The Flex Credit footnote said to sign between November 4 and November 8, 2026, and close and fully fund by November 20. Either way, by November 8 the washer-and-dryer window had closed, and the Flex Credit was at its last day at best. Under either set of published dates, the contract window has now ended, so read this section as a record of the offer, not an open deal. If a Lennar homesite catches your eye, ask the sales office what it’s offering now and whether that home qualifies. Don’t plan around November 27.
D.R. Horton: “All closing costs covered” through November 14
D.R. Horton’s sales team sent a Southern Virginia flyer on November 6, 2026, advertising “All Closing Costs Covered For a Limited Time!” It doesn’t use the Black Friday name.
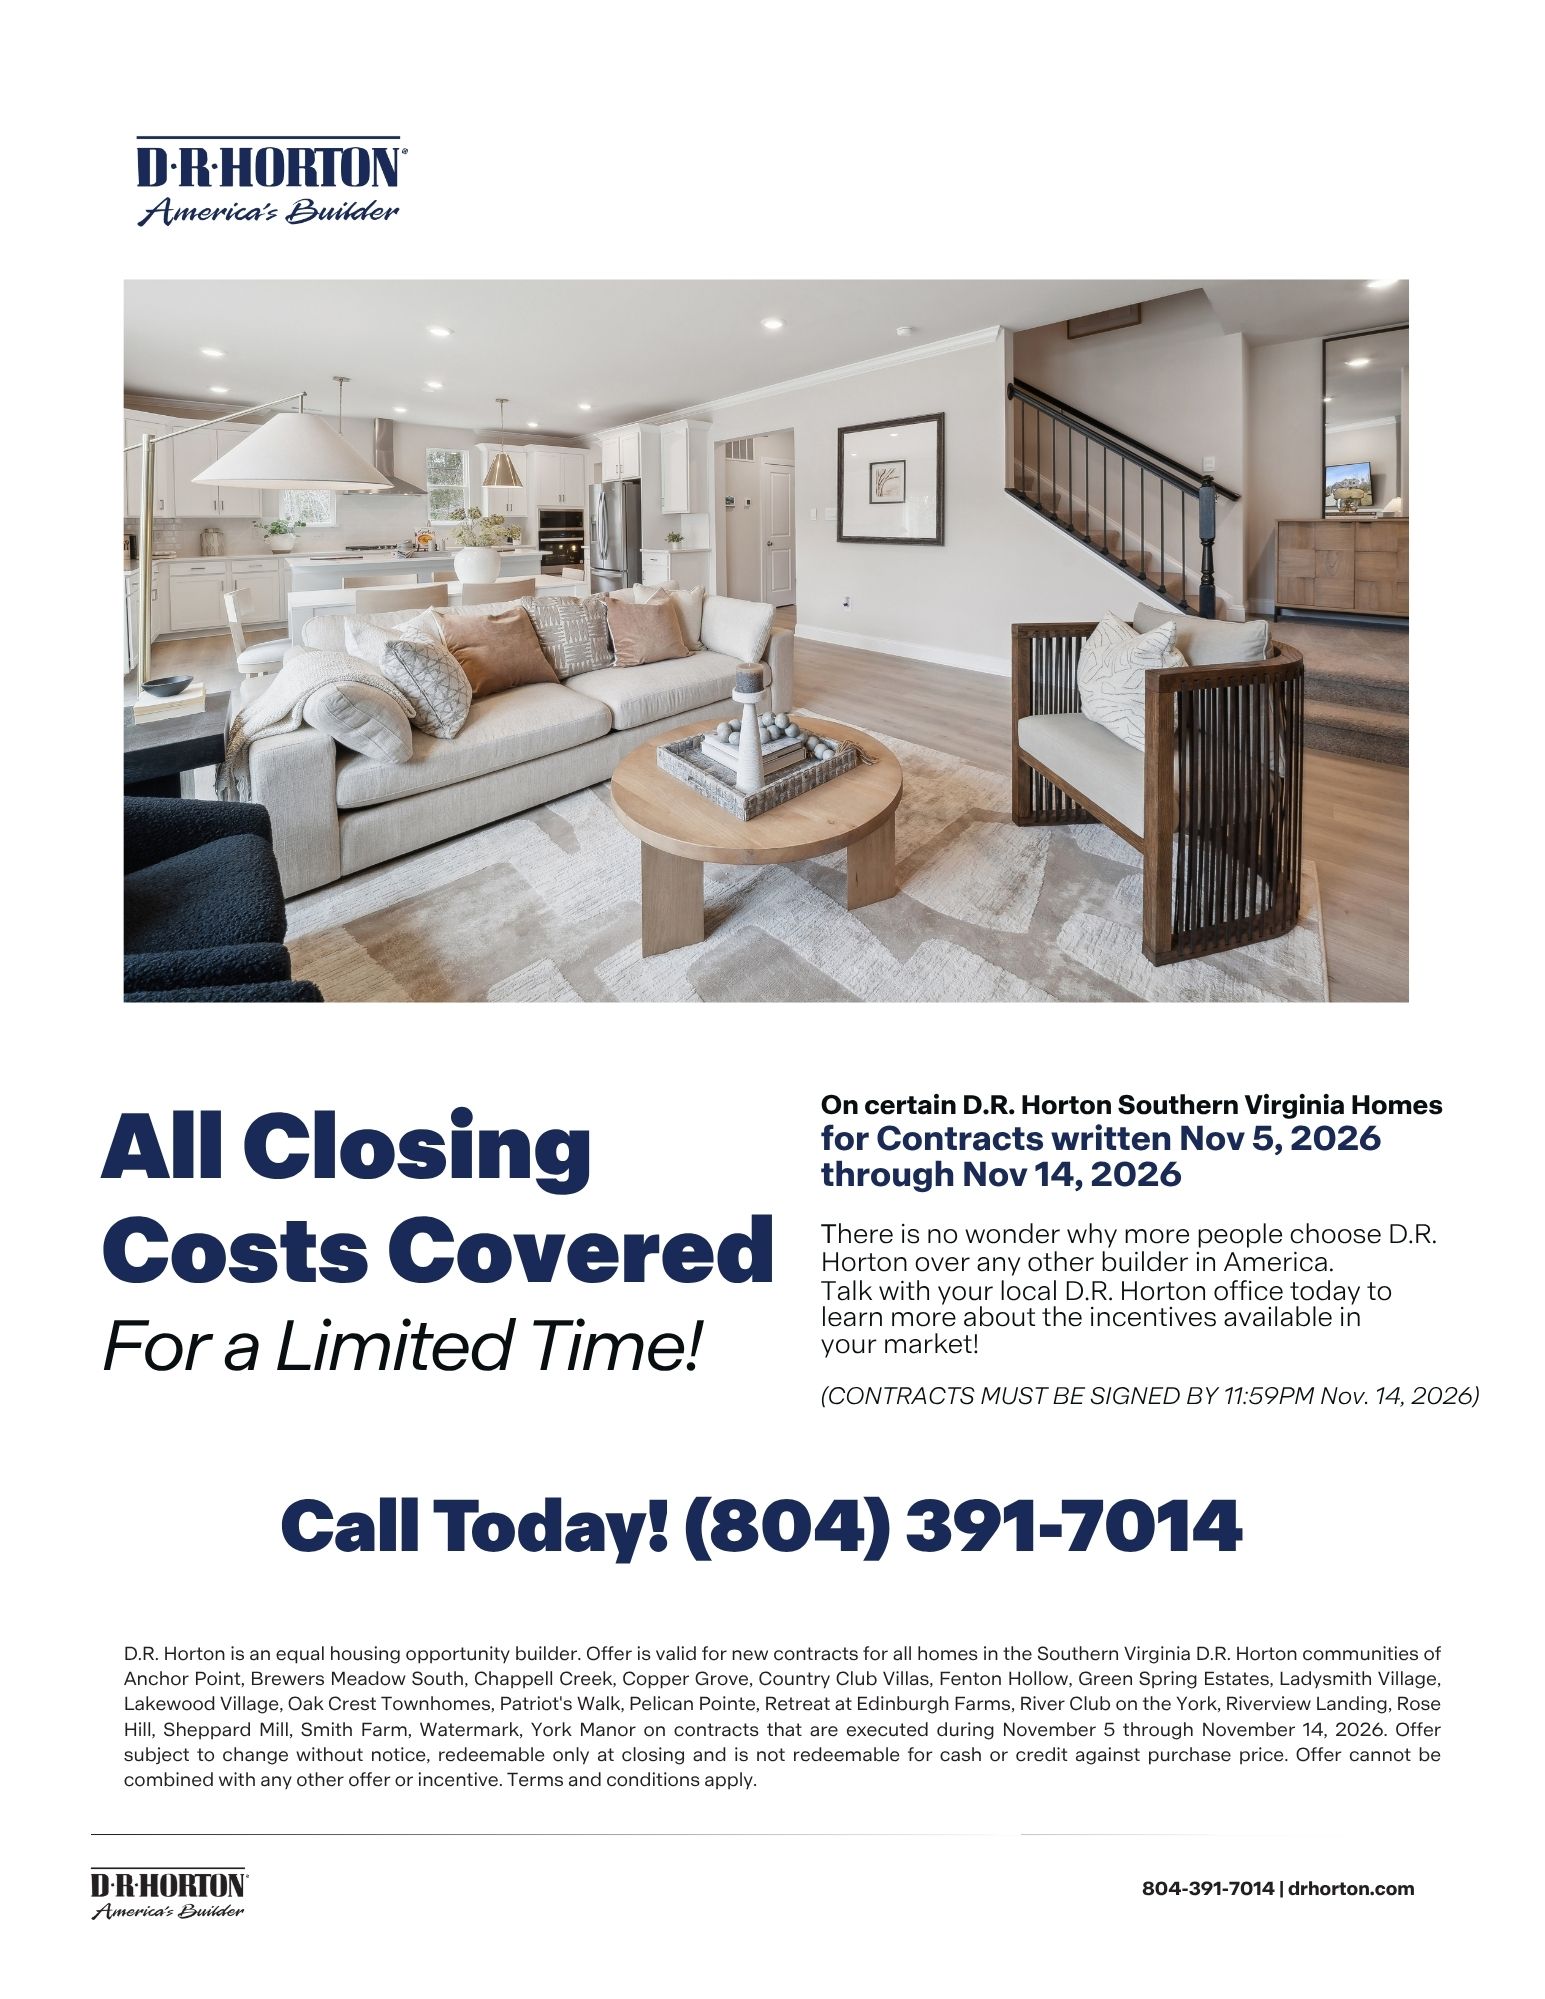
The headline says the offer applies “on certain D.R. Horton Southern Virginia Homes.” The fine print gets more specific. It covers new contracts for all homes in a named list of communities, executed November 5 through November 14, 2026, and signed by 11:59 p.m. on November 14.
Named communities in or near Greater Richmond include Watermark and Copper Grove in Chesterfield, Oak Crest Townhomes in Mechanicsville, Sheppard Mill and York Manor in Henrico, Anchor Point in Hopewell, Lakewood Village and Chappell Creek in Prince George County, and Ladysmith Village in Ruther Glen. If a community isn’t on the flyer, don’t assume it qualifies.
The restrictions:
- Redeemable only at closing, not for cash or a credit against the purchase price
- Can’t be combined with any other offer or incentive, and subject to change without notice
- No dollar cap, required lender, or list of covered fees is stated
That last point matters. Closing costs aren’t your down payment, and the flyer doesn’t say your down payment or prepaid items are covered. Ask for a written estimate of the seller credit that will show on your closing disclosure.
Main Street Homes: 5.75% initial rate on a 10-year ARM
Main Street Homes is advertising a 5.75% initial rate (6.296% APR in its published example) for contracts ratified November 1 through November 30, 2026. It’s a conventional 10/6 adjustable-rate loan, fixed for the first 10 years and then able to adjust. It’s not a 30-year fixed rate.
The published example assumes a 10% down payment, a 780 credit score, owner occupancy, a $500,000 purchase price, and a maximum loan of $845,000. The offer is only available through the builder’s designated preferred lender, on select to-be-built and quick move-in homes, in lieu of all other incentives. Funding comes from a limited pool, first come, first served, so the offer can end before November 30. The fine print also references closing by November 22, 2027, or the scheduled settlement date, whichever comes first. Confirm the settlement deadline for your specific home.
Eastwood Homes: closing-cost help and a holiday scratch-off
Eastwood Homes lists several “limited time” closing-cost offers on select quick move-in homes when you use an Eastwood preferred lender. Amounts vary by community, so look at the specific home, not the biggest number. As of November 9, Richmond-area examples included up to $15,000 or $20,000, depending on the home, at Mountainwood Crossing in Glen Allen and up to $16,500 at The Townes at Mount Hermon in Moseley. No end date is posted for these.
Eastwood is also running its Big Red Bow holiday promotion in Richmond, a scratch-off certificate for new contracts between November 1 and December 31, 2026. The Richmond gift amounts aren’t posted, and incentives vary by home and community, so ask a New Home Specialist.
Miller and Smith: half off options at Sadler Square
At Sadler Square in Glen Allen, Miller and Smith is offering half off options, up to $40,000, on to-be-built Maison or Crosby floor plans for new sales agreements through December 31, 2026. You have to use its preferred lender, loan officer, and title company. The credit can’t lower the price, and it can’t be combined with any other incentive. It’s an options credit, not closing-cost or down-payment help.
Compare the whole loan, not the headline
You can’t compare a rate promo and a closing-cost credit directly. The Consumer Financial Protection Bureau explains that APR includes points and other loan charges, so it’s usually higher than the interest rate. On an adjustable-rate loan, APR also doesn’t show the maximum rate the loan can reach.
Before you count any incentive:
- Confirm the exact community and homesite qualify, not just the metro.
- Write down both the contract deadline and the closing deadline, and ask which controls if a page shows 2 sets of dates.
- Find out which lender, loan officer, or title company is required, and whether the offer combines with anything else.
- For a rate, get the note rate, APR, loan type, and whether any buydown is temporary or permanent.
- For closing-cost help, ask what’s covered, whether there’s a cap, and whether prepaids are included.
- Compare Loan Estimates from the builder’s lender and an outside lender on the same day, including cash to close.
- If you want your own agent, ask each sales office how it handles buyer representation before your first visit, since policies vary.
Want help comparing a specific home?
Looking at a new home in Chesterfield, Henrico, Hanover, or a nearby county? I can help you check whether an incentive still applies to that address and how it compares with an outside lender’s quote. I’m a REALTOR®, Accredited Buyer’s Representative (ABR), Seller Representative Specialist (SRS), and Certified New Home Co-Broker with eXp Realty. Book a consultation.
This article is for general education. It isn’t a loan offer, a commitment to lend, or legal or tax advice, and I’m not a lender. Offers come from builder pages and the D.R. Horton Southern Virginia flyer as they appeared on November 8, 2026, and they can change or end without notice. Confirm current terms, eligibility, and deadlines with the builder and your loan officer in writing. Equal Housing Opportunity.